


If you're considering investing in UK property, one of the first decisions you'll face is whether to buy a rental property yourself or invest through a property fund.
Both routes allow you to benefit from the UK's robust real estate market, but they offer completely different experiences. Direct buy-to-let ownership puts you firmly in control, giving you the ability to use mortgage leverage and force the value of the property up through refurbishment. Conversely, property funds offer a completely hands-off experience, allowing you to invest in large-scale commercial and residential buildings while professional managers handle the day-to-day operations.
Whether you are just starting out or refining a broader personal investment plan, understanding the mechanics, tax implications, and returns of each strategy is essential. This comprehensive guide compares property funds, Real Estate Investment Trusts (REITs), and direct buy-to-let property to help you decide which route aligns best with your financial goals.
Executive Summary
This guide provides a comprehensive comparison between direct buy-to-let ownership and indirect property funds to help UK investors allocate their capital effectively. The choice ultimately depends on your available capital, desired level of operational involvement, and specific tax circumstances. If you're deciding between property and other asset classes before making this choice, see our guide to is property a good investment?
Key Takeaways:
- Property Funds: Best for hands-off, passive investors who want instant diversification across large-scale assets and have smaller amounts of starting capital.
- Buy-to-Let: Best for active investors who want to use mortgage leverage, exercise absolute control over their assets, and force capital appreciation through strategic refurbishments.
- Tax Differences: REIT property funds are highly tax-efficient (especially when dividends are shielded inside an ISA or SIPP), whereas individual buy-to-let landlords face increasingly strict Section 24 tax rules governing mortgage interest relief.
What Is a Property Investment Fund?
A property investment fund is a pooled investment vehicle that allows multiple investors to combine their money to buy and manage real estate without having to own the buildings directly. Professional managers handle the assets, allowing you to earn returns completely passively.
Instead of buying a single house or flat, you purchase units or shares in a fund. The fund manager then uses this massive pool of capital to buy institutional-grade real estate.
Imagine you invest £20,000 into a UK property fund. Your money could end up spread across dozens of logistics warehouses, prime city-centre office blocks, and large-scale apartment complexes. You do not need to worry about fixing a leaking roof or finding tenants; the professional management team handles all asset selection, tenant negotiation, and structural maintenance.
These funds are strictly regulated by the Financial Conduct Authority (FCA) to ensure investors are protected and systemic risks are managed. By acquiring units in these regulated entities, you shift from being an active landlord to a passive shareholder.
Property Funds vs Buy-to-Let
Before diving deeper into the specific types of funds, it is crucial to understand how they compare to traditional direct property ownership. This is the biggest decision most investors face.
The table below highlights the fundamental differences:
Control and Value-Add Potential
With a direct buy-to-let, you hold the reins. You choose the property, decide on the tenant, and control the timing of any upgrades. This active involvement allows you to force appreciation. For example, by converting a standard house into a House in Multiple Occupation (HMO), you can significantly boost your rental yields, sometimes pushing them past 10%.
Property funds offer zero control. Your investment is entirely passive, meaning you cannot actively increase the value of the assets. However, this lack of control is exactly what appeals to busy professionals who do not want the hassle of managing property.
Tax and Section 24
Tax is one of the most critical divergence points. Over the last decade, the introduction of Section 24 by HM Revenue & Customs (HMRC) has severely impacted individual buy-to-let landlords. Under these rules, individual landlords cannot deduct their mortgage interest from their rental income before calculating tax; instead, they receive a basic 20% tax credit. For higher-rate taxpayers, this often results in large tax bills on their gross rental revenue, pushing some landlords into negative cash flow.
While landlords can bypass this by buying properties through a Limited Company, which allows them to deduct mortgage interest as a business expense, this requires careful structuring.
Conversely, property funds like UK REITs are incredibly tax-efficient. They are exempt from UK corporation tax on their rental profits. If you hold your REIT shares within a Stocks and Shares ISA or a pension, your dividend income can be entirely tax-free.
Leverage and Capital Needed
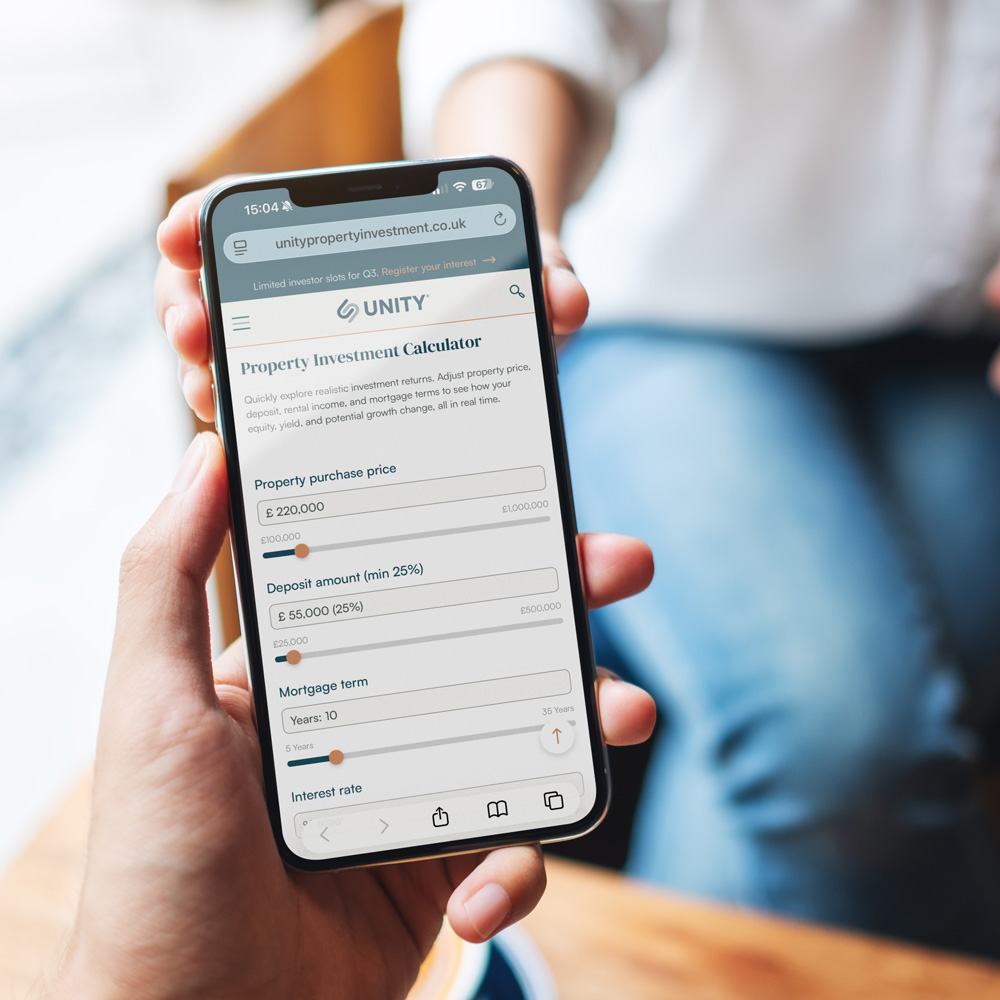
If you're unsure how much capital you'll need, read our guide on how much money do you need to invest in property? Physical buy-to-let generally requires a substantial deposit (often 25% of the property value), plus legal fees and Stamp Duty surcharges. However, this allows you to use a buy-to-let mortgage to leverage your investment, amplifying your potential returns.
Property funds require vastly lower initial capital, often just a few hundred pounds, but you generally cannot use a mortgage to buy fund units, meaning you cannot magnify your returns through debt.
How Do Property Funds Work?
Property funds pool investors' money to buy and manage property. Investors earn returns from rental income and capital growth without directly owning or managing buildings.
When you invest in a fund, professional managers deploy your capital. Returns are generated in two ways:
- Rental Income: The tenants leasing the commercial or residential buildings pay rent, which is collected and distributed to you as dividends.
- Capital Growth: Over time, the physical buildings may increase in value. When independent valuers assess the properties, the unit price of your fund adjusts accordingly.
Property Funds vs REITs
Many investors confuse general property funds with REITs. While all REITs are property funds, not all property funds are REITs. Understanding the structural differences is vital for managing your liquidity and tax.
Property funds offer a completely hands-off experience, allowing you to invest in large-scale commercial and residential buildings while professional managers handle the day-to-day operations.
While property funds leave you at the mercy of the broader market, direct buy-to-let puts you firmly in the driving seat of your financial future.
Closed-ended funds, like UK REITs, issue a fixed number of shares that trade on the stock market. You can buy and sell them instantly. Because their price is determined by the stock market, they can trade at a discount or a premium to the actual value of the underlying buildings.
Open-ended funds, like the new long-term asset fund (LTAF), issue new units when you invest and cancel them when you withdraw. Because selling a physical skyscraper takes months, open-ended funds cannot always return your money immediately. New regulations now mandate a minimum 90-day notice period to withdraw your money from an LTAF, ensuring the fund is never forced to sell buildings cheaply during a panic.
Types of UK Property Funds
If you decide to invest indirectly, you are not limited to a single sector. Funds are heavily segmented, allowing you to choose exactly what type of real estate your money supports.
Residential Property Funds UK
The UK residential sector has seen a massive influx of institutional money over the last decade, primarily focused on Build-to-Rent (BTR) developments.
BTR involves purpose-built, large-scale apartment complexes designed exclusively for renting. They offer hotel-style amenities such as gyms, co-working spaces, and concierge services. Because of these premium features, BTR properties command rents approximately 9.3% higher than standard local housing, while experiencing much lower void rates.
Commercial Property Funds UK
Commercial property funds invest exclusively in business real estate. This sector operates differently from residential property because of the types of leases involved. Typical commercial sectors include:
- Offices: Ranging from regional business parks to prime central London towers.
- Industrial and Logistics: Warehouses and distribution centres that have boomed alongside e-commerce.
- Retail: Supermarkets and out-of-town retail parks.
A major benefit of commercial property is the Full Repairing and Insuring (FRI) lease, which legally transfers all internal and external maintenance costs directly to the commercial tenant.
UK Real Estate Funds
When exploring real estate investment funds in the UK, broadly diversified options might appeal to you, especially if you are searching for low risk UK investments. Instead of picking one sector, these funds spread your capital across residential complexes, industrial warehouses, and retail parks simultaneously. This extreme diversification insulates your portfolio from localised economic shocks.
Property Fund Returns
When evaluating a fund, you need to look at both the income yield (the rent) and the capital appreciation (the growth in property value).
Historically, long-term gross yields across the UK commercial sector average between 4.5% and 6.0%. Total returns fluctuate based on the broader economy and interest rates. For instance, over the 12 months to February 2025, the broader UK real estate market achieved a total return of 8.1%, heavily driven by strong performance in retail and industrial warehouses, according to data from the MSCI UK property index.
However, returns can be negative. When the Bank of England raises interest rates rapidly, the cost of borrowing increases, which can drag down the capital value of commercial buildings, as seen when secondary office values declined by 4.6% in recent years.
Finally, you must account for fees. Actively managed funds typically charge an ongoing fee (Total Expense Ratio) of 1.00% to 1.50%, whereas passive funds that track an index might charge as little as 0.40%.
Best Property Funds UK
There is no single "best" property fund. Finding the best property investment funds for your portfolio depends entirely on your strategy. For investors with a specific budget, our best way to invest £100k guide explores how property compares with stocks and other investments to help you shape your portfolio.
Institutional investors frequently compare funds from major asset managers such as BlackRock, Legal & General, M&G, Schroders, and Aviva. Please note that mentioning these firms is purely illustrative to explain how investors compare options, rather than a recommendation to invest with them.
When comparing these heavyweights, sophisticated investors evaluate:
- Occupancy Rates: High void rates indicate poor management or undesirable locations.
- Fees: A high management fee eats directly into your dividend yield.
- Debt Levels: Funds that carry too much floating-rate debt suffer when central bank interest rates rise.
- Sector Focus: Some investors prefer the defensive stability of supermarkets, while others chase the capital growth of industrial logistics.
Pros and Cons of Property Funds
✓ Pros:
- Low Barrier to Entry: You can invest in prime real estate for the cost of a single share, rather than saving tens of thousands for a mortgage deposit.
- Instant Diversification: Your money is spread across multiple buildings, tenants, and regions, severely reducing your risk.
- Completely Passive: Professional managers handle all maintenance, tenant disputes, and legal compliance (such as EPC regulations).
- High Liquidity: Shares in listed REITs can be bought and sold in seconds during trading hours, unlike physical houses that take months to convey.
✗ Cons:
- No Leverage: You cannot take out a mortgage against your fund units to aggressively grow your wealth.
- Management Fees: Ongoing charges will constantly drag down your net returns.
- Zero Control: You have no say over which properties are bought or sold, or how they are managed.
- Market Volatility: The price of listed property funds often fluctuates with the broader stock market, sometimes dropping well below the actual value of the buildings they own.
Portfolio projection tool

Which Option is Right for You?
Deciding between an indirect fund and a direct buy-to-let property comes down to your personal capital, your timeline, and how much work you want to do. If you are currently evaluating the best way to invest £50k or looking at investing an inheritance / generating income from £100k, carefully weigh the desire for hands-off dividends against the powerful wealth-building potential of leveraged physical property.
Choose a property fund if:
- ✓ You want entirely passive investing with zero tenant management.
- ✓ You have a smaller starting pot (e.g., under £20k) and cannot afford a property deposit.
- ✓ You want broad diversification across massive commercial asset classes.
- ✓ You are investing through an ISA or SIPP and want tax-free dividends.
Choose buy-to-let if:
- ✓ You have a larger deposit saved up (e.g, £50k+).
- ✓ You want to use mortgage leverage to safely amplify your capital growth.
- ✓ You want to build equity that you can eventually refinance and pull out.
- ✓ You want absolute control over your assets and the ability to add value.
Quick Decision Summary
Conclusion
The UK property market offers excellent opportunities for wealth generation, but the route you choose will drastically shape your day-to-day experience as an investor.
For investors seeking entirely passive exposure, property funds can be an excellent option. They provide a convenient, heavily diversified way to gain exposure to real estate without the regulatory headaches of tenant management, making them ideal for busy professionals and pension investors.
However, for those looking to build a long-term portfolio with greater control, direct buy-to-let offers opportunities that pooled funds simply cannot match. Many sophisticated investors ultimately choose direct ownership because it serves as a powerful engine for active wealth creation. Owning physical property gives you absolute control over the asset. It allows you to utilise mortgage leverage to safely amplify your returns, meaning your wealth can grow much faster than it would in an unleveraged fund.
Furthermore, direct ownership gives you the freedom to actively add value. You can refurbish a property to force its capital value up, increase the rent to improve your yields, and eventually refinance the asset to pull out tax-free equity to fund your next purchase. While property funds leave you at the mercy of the broader market, direct buy-to-let puts you firmly in the driving seat of your financial future.
Unlisted Property Funds vs Listed REITs
Feature
Traditional Property Fund (Unlisted)
REIT (Listed)


Get investor insights and early access to opportunities
Join our investor briefings for structured insights, market updates, and priority access to new deals.

No spam, just timely insights for investors We respect your privacy and never sell your data
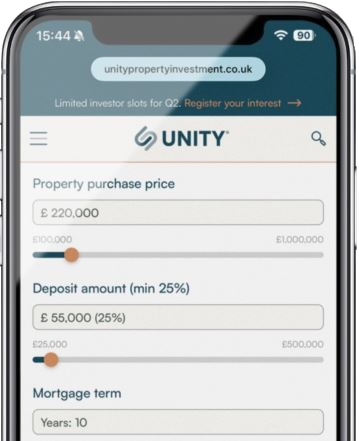
Buy to let investment and rental yield calculator
Property Fund vs Buy-to-Let Comparison
Feature
Property Fund
Buy-to-Let
Quick Decision Summary Matrix
If you want...
Better option
Frequently Asked Questions
What is a property investment fund?
How do property funds work?
Are property funds a good investment?
Can you lose money in a property fund?
Are REITs the same as property funds?
Should beginners buy a property fund?
Case study
- Property Price:£275k
- Mkt Value at purchase:£290k
- Day one equity:£14,500
- Yield:7.2%
- ROCE:28.6%