




Rental supply is tightening and rents are accelerating, yet professional property investors are planning further acquisitions. Rather than a straightforward landlord exodus, the latest evidence suggests the UK buy-to-let market may be going through a more significant change in ownership and investment behaviour.
For several years, the dominant narrative around UK buy-to-let has been relatively straightforward. Higher borrowing costs, increased taxation and a more demanding regulatory environment have made property investment less attractive to some landlords, prompting sales and contributing to pressure on the supply of homes available to rent.
There is clearly some truth in that argument. Some landlords have left the market, while others continue to reassess whether individual properties justify the capital and work involved in owning them.
Recent rental market data, however, suggests something more complicated is happening.
BBC News recently reported that rent rises are expected to accelerate, following new data showing that rental growth has started to pick up again. According to Zoopla's September 2026 Rental Market Report, rents on newly agreed tenancies were 2.6% higher than a year earlier in July, having recovered from annual growth of 1.6% in February. Zoopla now expects rental growth to reach between 4% and 5% by the end of 2026.
At the same time, rental supply has started to fall again. The number of homes available to rent is 3% lower than a year ago, while the flow of new rental properties coming to market is down 6%.
Those figures might appear to support the familiar landlord exit narrative: fewer landlords, fewer rental properties and consequently higher rents.
Yet Handelsbanken's latest Property Investor Report presents another side of the market. Its research found that 84% of the professional property investors, landlords and property management professionals surveyed intend to increase their property holdings over the next 12 months, compared with 54% in the previous year's survey. Only 1% intend to exit property investment completely.
These findings raise a more interesting question for investors. What if the UK private rented sector is not simply contracting, but also changing hands?
Executive Summary
The latest evidence suggests that the UK buy-to-let market is becoming more selective. Rental supply is tightening and rental growth is accelerating, but professional investors are simultaneously increasing their appetite for acquisitions. Rising landlord-to-landlord transactions add to the evidence that part of the apparent landlord retreat is actually a transfer of property between different types of owners.
Key takeaways
- Rental growth has started to accelerate again. New-let rents were 2.6% higher year-on-year in July, up from 1.6% in February, with Zoopla forecasting growth of 4% to 5% by the end of 2026.
- Rental supply is tightening. Available rental homes are down 3% year-on-year and the flow of new rental properties is down 6%, increasing competition between tenants.
- Professional investors are not retreating. Handelsbanken found that 84% of its professional investor sample intends to expand property holdings over the next 12 months.
- The investment opportunity is becoming more dependent on selection. Higher rents do not automatically produce higher net returns. Acquisition price, financing, operating costs, tenant affordability and resale liquidity remain critical.
Rental growth is accelerating again
The immediate development attracting attention is the return of stronger rental growth.
Zoopla recorded average UK rents for new lets at £1,343 per month, 2.6% higher than a year earlier. While that remains considerably below the exceptional rental inflation seen earlier in the decade, the direction of travel has changed. Annual rental growth had fallen as low as 1.6% in February 2026 before beginning to accelerate again.
Growth over the six months to July was running at an annualised rate of around 4%, which led Zoopla to increase its forecast for rental growth by the end of the year to between 4% and 5%.
Official figures also show rental growth strengthening, although they measure a different part of the market. The Office for National Statistics recorded average UK private rents increasing by 3.7% in the year to July 2026, up from 3.3% in June. Average monthly rent across the UK reached £1,393.
The distinction between these measures is important. Zoopla's data focuses on rents for newly agreed lets, while the ONS Price Index of Private Rents incorporates new and existing tenancies. Neither figure should therefore be interpreted as suggesting that every landlord is currently achieving rental increases of between 3.7% and 5%.
What matters is the direction of travel. Several indicators now suggest that the period of rapidly slowing rental growth has ended, at least for now.
This builds on a trend Unity examined previously in Rents Are Now Outpacing House Prices: What This Means for UK Rental Yields. With UK house-price growth remaining relatively subdued while rents continued to increase, gross rental yields had already begun to improve in parts of the market.
The latest development is that the supply side of that equation has started to tighten again.

Buy to let investment and rental yield calculator

Falling rental supply may matter more than the headline rent figure
For a property investor, a forecast of 4% to 5% rental growth is interesting. The change in rental availability may ultimately be more significant.
Zoopla reports that the number of homes available to rent is now 3% lower than a year ago, ending three years of improving supply. The flow of new homes coming onto the rental market is 6% lower, while total rental availability remains around 25% below its pre-pandemic level.
Competition between tenants has consequently begun to increase again. There are now an average of 5.3 enquiries for every available rental home, 6% more than a year ago and the highest level for almost two years.
The relationship between supply and rental growth is also visible geographically. Zoopla's analysis shows a clear relationship between changes in rental availability and the pace of rental growth.
This matters because rental growth does not depend solely on the number of people looking for somewhere to live. It depends on the balance between that demand and the number of properties available to meet it.
Higher mortgage rates are adding another dimension. Zoopla estimates that the average prospective first-time buyer now needs an additional £18,200 deposit to maintain the same mortgage repayment following the rise in mortgage rates this year. In London, that figure rises to £35,500.
For some prospective buyers, that delays the transition from renting into home ownership. Households that might otherwise have left the private rented sector can therefore remain tenants for longer.
For existing landlords, tighter supply can support occupancy and provide greater scope for rental growth. For prospective investors, however, that does not automatically make every rental property more attractive.
To understand why, it is necessary to look at what is happening to landlord ownership.
The landlord exodus narrative does not tell the whole story
Landlords are selling properties. The pressures encouraging some of them to do so are real.
Higher borrowing costs have had a particularly significant effect on owners who acquired property with substantial leverage during the era of very low interest rates. A rental property that produced acceptable cash flow with mortgage finance at 2% or 3% can look very different when that debt is refinanced at today's rates.
Individual higher-rate taxpayers also continue to operate under restrictions on mortgage interest relief. Maintenance, insurance and compliance costs have increased, while the regulatory requirements associated with managing rental property are becoming more demanding.
The Renters' Rights Act adds another layer to that changing operating environment. Unity has examined the legislation separately in Renters’ Rights Act: What the First 100 Days Mean for Property Investors, including the implications for possession, rent reviews and professional property management.
Importantly, these pressures do not affect every landlord equally.
An investor with low leverage, substantial liquidity and several properties may respond very differently from an individual landlord approaching refinancing on a single highly leveraged property.
That distinction becomes important when interpreting claims of a landlord exodus.
Recent transaction evidence suggests that a growing proportion of rental properties being sold are subsequently acquired by another landlord.
According to Hamptons' Summer 2026 Market Insight, 23% of the properties acquired by landlords during the first four months of 2026 had previously been let. That compares with 16% during 2025 and an average of 9.9% between 2019 and 2023.
Hamptons also found that landlords accounted for 13.3% of all residential purchases between January and April 2026, their highest share of transactions since 2016.
These figures require some caution. They do not mean that rental supply is stable, nor do they suggest that every property sold by a landlord is bought by another investor. Properties are undoubtedly leaving the private rented sector and returning to owner occupation.
What they do show is that gross landlord sales cannot automatically be treated as net landlord exits.
A property can cease to work for one investor while remaining an attractive investment for another.
That leads to a more useful question than simply asking whether landlords are leaving buy-to-let: which landlords are selling, why are they selling, and who is buying from them?
A property can cease to work for one investor while remaining an attractive investment for another.
A more demanding buy-to-let market is not necessarily a weaker investment market.
Why professional investors are responding differently
The Handelsbanken findings become particularly interesting in this context.
Its research is not representative of every UK landlord. Handelsbanken surveyed 200 UK real estate investors, property management professionals and landlords. Respondents managed an average of 35 properties, making this a considerably more professional cohort than someone owning a single buy-to-let property alongside another occupation.
Among this group, sentiment appears markedly different.
Some 84% intend to increase their property holdings over the next 12 months, up from 54% in Handelsbanken's 2025 survey. A further 93% expect the value of their portfolios to increase. Just 1% expect to leave property investment completely.
The reasons for wanting to expand are perhaps more revealing than the headline figure. Among investors planning further investment, 70% cited buying opportunities or current property valuations, while 58% cited strong rental demand. The availability of finance was cited by 33%.
Taken together, the latest evidence shows why the current buy-to-let market is more nuanced than a straightforward landlord exit story.
The table also highlights something important. Professional investors are not simply looking at a forecast for rising rents and concluding that buy-to-let has become attractive again. Acquisition pricing is a central part of the decision.
There is a logical reason for this.
If part of the landlord market is under pressure from refinancing, taxation or changing investment priorities, prospective buyers may encounter sellers who place greater value on certainty and speed of execution. At the same time, weaker house-price growth can improve the relationship between purchase price and achievable rent.
Unity considered the pricing side of this equation in Are Falling Southern Property Prices Creating a Buying Opportunity for Investors?. Falling prices alone do not make an investment attractive. They can, however, create a better entry point when rental demand and the underlying economics remain sound.
This may help explain the apparent contradiction in the current market.
Buy-to-let can become less attractive to one owner at exactly the same time that the same property becomes more attractive to another.
The difference can lie in acquisition price, financing, ownership structure, available capital, investment horizon or the investor's ability to operate the property efficiently.
From landlord exit to ownership transfer
Consider a landlord who acquired a rental property several years ago and is now approaching refinancing.
The property's value may have risen only modestly. The mortgage rate available today may be substantially higher than the rate being replaced. The owner may also be facing maintenance expenditure or considering whether the return still compensates them for the capital tied up in the property.
Selling can be a perfectly rational investment decision.
A new investor can look at exactly the same property and reach a different conclusion.
They may be able to negotiate a lower acquisition price, finance the property at a lower loan-to-value and undertake improvements that support a stronger market rent. Their tax position, financing costs and intended holding period may also differ from those of the seller.
The physical property is the same. Its economics to the new investor are not.
This is why the increase in landlord-to-landlord transactions is potentially significant. It suggests that part of what is described as landlord retreat may actually be capital moving between different types of property owners.
It would be premature to describe this as a complete restructuring of the private rented sector. Smaller private landlords will continue to play a substantial role in UK rental housing.
There is, however, growing evidence that the operational threshold for successful buy-to-let investment is rising.
Is UK buy-to-let becoming more professional?
One indication is the continued growth of corporate ownership.
Hamptons' analysis of Companies House records identified 469,165 active property businesses in Great Britain by the end of August 2026. While the rapid pace of company formation has started to slow, the nature of the activity appears to be changing.
For the first time, new purchases represented 51% of properties entering limited-company structures in 2026, rather than transfers of properties already owned personally.
This does not mean that using a limited company automatically makes someone a professional investor. Nor is incorporation necessarily the most appropriate ownership structure for every buyer.
It does form part of a wider pattern.
Handelsbanken found that professional investors are also changing how they operate in response to the regulatory environment. Some 59% said they were tightening tenant selection criteria, while 56% were investing in property improvements.
This is an important aspect of the market that can be missed when the debate is reduced to whether landlords are buying or selling.
The demands of owning rental property are becoming increasingly operational. Property condition, compliance, tenant selection, financing, maintenance planning, rental affordability and portfolio cash flow need to be considered together.
Unity's view is that these changes are consistent with a gradual professionalisation of the UK private rented sector.
That does not necessarily mean institutional ownership replacing private landlords. A professional investor can own two houses or two hundred. The distinction is increasingly about how an investment is selected, financed and managed.
Portfolio projection tool
Higher rents do not automatically mean higher returns
There is an obvious danger in interpreting the current rental data too positively.
If rent rises by 5%, an investor's return does not automatically increase by 5%.
Gross rental income is only the first line in the investment calculation. Mortgage interest, property management, insurance, repairs, compliance, void periods, refurbishment expenditure and taxation all sit between headline rent and the return ultimately received by an investor.
Some of these costs have increased materially.
This can be particularly important in markets offering very high headline yields. Many property maintenance costs do not fall proportionately with the value of the house. Replacing a boiler, repairing a roof or undertaking electrical work can cost broadly similar amounts on a £100,000 property and a £300,000 property.
As a result, a high gross yield on a low-value property can be considerably less attractive once the cost of maintaining and operating the asset is taken into account.
Tenant affordability provides another constraint.
Rental supply can tighten without giving landlords unlimited pricing power. As rents increase, households can respond by moving to cheaper areas, choosing smaller properties, sharing accommodation or delaying a move altogether.
There is evidence of this behaviour in the market. Rightmove has previously reported tenants expanding their search areas as rental affordability became more challenging, demonstrating how households can adjust where they look rather than simply accepting any asking rent.
At some point, an asking rent can exceed what the local market will sustainably support.
For investors, the relevant distinction is therefore between headline rental growth and sustainable rental income.
A 10% yield is not necessarily better than a 7% yield
This is also why gross yield should not be used in isolation when comparing investments.
Suppose one property produces a 10% headline yield but sits in a market with weaker employment, higher tenant turnover, significant refurbishment requirements and limited owner-occupier demand.
Another produces 7%, but is located in an established employment market with broad tenant demand, lower expected maintenance expenditure and strong resale demand from first-time buyers.
The first property has the higher gross yield. It does not automatically have the better risk-adjusted return.
Investors need to consider the durability of the income, not simply its size.
That includes the cost of producing the rent, the likelihood of void periods, the condition of the building, the affordability of the rent to the target tenant and the range of buyers likely to want the property when it is eventually sold.
This is one reason Unity's investment approach focuses on the relationship between income, acquisition price and long-term asset quality rather than simply screening the market for the highest available gross yield.
The national picture hides very different regional markets
The latest data also reinforces how misleading it can be to talk about the UK rental market as though it were homogeneous.
According to the latest ONS private rental data, annual private rent inflation in England ranged from 6.3% in the North East to 2.9% in the South East in July. England as a whole recorded 3.8% growth, while Wales recorded 4.5% and Scotland 1.7%.
Supply conditions vary considerably too. Zoopla's latest research shows that the availability of rental homes is contracting more sharply in some regions than others.
Property prices, wages, employment markets and rental affordability also differ significantly.
A national forecast of 4% to 5% rental growth should therefore never be applied mechanically to an individual investment appraisal.
Unity examined these regional differences in more detail in Why Regional Rental Yields Don't Tell the Whole Story.
The relevant question is not simply which region has the highest average yield. It is whether a specific local market offers an attractive relationship between purchase price, sustainable rent, operating costs, tenant demand and future resale value.
In practice, that analysis needs to happen at town and property level.
What should investors take from the changing market?
The current environment potentially creates opportunities, but it also raises the standard of analysis required before buying.
The first principle is not to rely on forecast rental growth to make an investment work.
Zoopla's expectation that UK rental growth could reach 4% to 5% by the end of 2026 is a forecast, not guaranteed income. A property should make sense based on a realistic assessment of today's achievable rent. Future growth should strengthen the investment case rather than rescue it.
The second is to look beyond gross yield.
Investors should estimate the likely cost of maintaining the property, management, insurance, compliance and periods without rent. Financing can then be considered separately so that the underlying performance of the asset can be distinguished from the effect of leverage.
Third, local tenant affordability matters. A shortage of rental property is supportive only while tenants can continue to afford the rent being asked. Local wages and the depth of the target tenant market therefore matter alongside portal asking rents.
Fourth, acquisition price remains fundamental.
If greater numbers of landlords are reconsidering portfolios, investors with available capital may encounter opportunities where the seller's circumstances create negotiating leverage. But a discount from an unrealistic asking price is not automatically good value. The final price still needs to be justified by the property's condition, achievable rent and comparable sales.
Finally, investors should consider how they will eventually exit.
A conventional two or three-bedroom house in a functioning owner-occupier market may appeal to another landlord when sold, but it may also appeal to a first-time buyer or family. That wider buyer pool can be valuable.
An investment property that can realistically be sold only to another yield-focused investor has a narrower exit route and may require a larger discount when market conditions weaken.
The opportunity may be in selection rather than market direction
There is a tendency in property investment to frame market conditions as either good or bad.
The current evidence suggests that distinction is becoming less useful.
Higher rents are positive for income, but higher financing and operating costs can absorb that benefit. Falling prices can improve acquisition yields, but they may also reflect weak local demand. Landlords selling can reduce rental supply, while those same sales can create opportunities for other investors.
The result is a market in which outcomes may increasingly diverge between individual properties and individual investors.
For someone buying indiscriminately, the operating environment may be considerably harder than it was during the period of ultra-low interest rates.
For someone able to identify a fundamentally sound property, negotiate an attractive acquisition price, finance it sensibly and manage it professionally, the same environment may present opportunities that were harder to find when capital was cheap and investor competition was stronger.
That appears broadly consistent with the behaviour captured by Handelsbanken's latest professional investor research. Investors are not ignoring the challenges facing the sector. They are adapting their portfolios and looking for opportunities created by those challenges.

Get investor insights and early access to opportunities
Join our investor briefings for structured insights, market updates, and priority access to new deals.

No spam, just timely insights for investors We respect your privacy and never sell your data
Unity view: the market is becoming more selective
The latest rental figures are supportive for landlords in several respects. Rental supply has started to tighten again, tenant competition remains elevated and rental growth appears to be accelerating.
But we think the more significant story for investors lies underneath those headline figures.
Some landlords are reassessing whether individual properties still meet their investment objectives as financing, taxation, regulation and operating costs change. At the same time, professional investors are reporting much stronger acquisition intentions and Hamptons' transaction data suggests that more rental properties are passing directly between landlords.
It is too early to conclude that the private rented sector is undergoing wholesale consolidation. The evidence does, however, suggest that describing the current environment simply as a landlord exodus misses an important part of what is happening.
Some rental property is leaving the sector. Some is staying exactly where it is, but under new ownership.
For investors, the distinction matters.
A more demanding buy-to-let market is not necessarily a weaker investment market. It is a market in which financing, asset selection, acquisition price and operational management have greater influence over the eventual outcome.
Rising rents alone will not determine which investments perform well.
The stronger opportunities are more likely to be found where investors can acquire good-quality residential property at a defensible price, achieve a sustainable rent supported by local incomes, control operating costs and retain a broad resale market.
If the UK rental market is becoming more professional, acquisition discipline may ultimately matter more than market direction.

What the Latest Buy-to-Let Data Is Telling Investors
Market signal
Latest evidence
What it could mean for investors
Sources: Zoopla Rental Market Report, Handelsbanken Property Investor Report and Hamptons Market Insight, 2026.
Case study
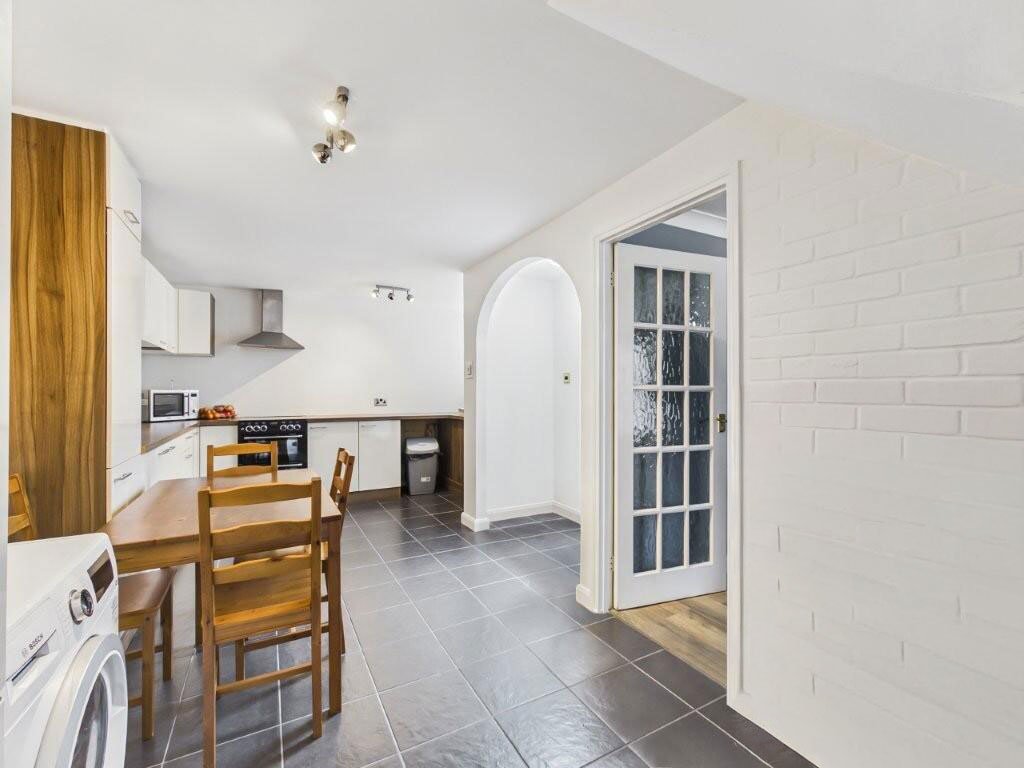
- Property Price:£275k
- Mkt Value at purchase:£290k
- Day one equity:£14,500
- Yield:7.2%
- ROCE:28.6%


